 E-Paper
 Sign In


UAE debt advice: What youth should do if loans, instalments become difficult to manage
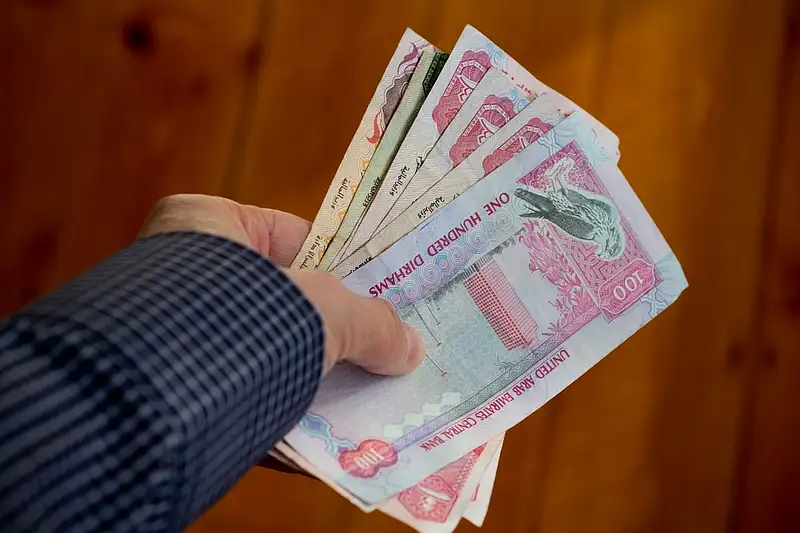
Financial professionals put the ideal level of monthly debt repayments at around 30 to 35 per cent of income
- PUBLISHED: Mon 17 Aug 2026, 2:05 PM UPDATED: Mon 17 Aug 2026, 2:52 PM


Young people struggling with loans, credit card balances or car instalments should start by taking a full look at what they owe, rather than taking on more debt to cover existing commitments, UAE financial experts have advised.
The advice follows a warning from Sharjah Ruler Sheikh Dr Sultan bin Muhammad Al Qasimi, who recently urged young people not to take on cars and other financial commitments they cannot afford.
Recommended For You
Stay up to date with the latest news. Follow KT on WhatsApp Channels.
“Don’t burden yourself with a car you cannot afford and get caught up in instalments, debts and other financial commitments,” Sheikh Dr Sultan said during a direct-line programme, urging young people to move away from such “bragging” and “come back down to earth”.
For young people who are already struggling with loan repayments, Terry Antoinette, a UAE-based finance professional, said the first step is to face the situation and write down every debt, including the outstanding balance, interest or profit rate and minimum monthly payment.
“The first step is not a financial one; it is an emotional one,” Antoinette said.
Having the full picture can turn what may feel like an overwhelming situation into something that can be addressed, he said.
Antoinette also advised borrowers to stop taking on new debt while they work on reducing their existing commitments and to speak to their bank before missing a payment.

“UAE banks have restructuring and consolidation options, and they are far more flexible with a customer who approaches them proactively than one who has already defaulted,” he said.
Abhishek Jain, CEO at Pesa Capital and EIRS, said borrowers should similarly begin by tracking their income and expenses and listing all outstanding debts and monthly instalments.
A realistic budget should then prioritise essential expenses such as housing, utilities, food and transportation, he said.
Which debt should be paid first?
Once essential expenses and minimum repayments are covered, borrowers need to decide where to direct any extra money.
Antoinette recommends paying the minimum on every debt before putting additional money towards the borrowing with the highest interest rate, which is often credit card debt.
“Mathematically, the highest rate is the enemy,” he said.
Jain said the consequences of missing a payment should also be considered. Car finance, for example, can be particularly important for someone who relies on their vehicle to get to work and earn an income.
High-interest credit card debt should also be tackled quickly, he said, while personal loans and other fixed-term borrowing can be addressed according to their interest rates and repayment schedules.
How much debt is too much?
Both financial professionals put the ideal level of monthly debt repayments at around 30 to 35 per cent of income.
Antoinette said total debt repayments, including car finance, should ideally remain below that range, while consumer debt such as credit cards and personal loans should account for no more than around 15 to 20 per cent.
Jain similarly said debt repayments should ideally stay below 30 to 35 per cent of monthly income. When 40 to 50 per cent of income is consistently going towards debt, he said, the level of borrowing can become financially unsustainable.
Antoinette said borrowers should aim to keep total debt repayments, including car finance, below 30 to 35 per cent of their income, with consumer debt such as credit cards and personal loans ideally accounting for no more than 15 to 20 per cent. He stressed that the UAE’s 50 per cent debt burden ratio is a regulatory ceiling, rather than a level people should aim to reach.
“If half your salary leaves your account on the first of the month before you have bought a single meal, you are not building a life; you are servicing one.”
He said the warning signs of excessive debt are not always reflected in a percentage, but can also be seen in a person’s financial behaviour.
“You are paying only minimums; you are borrowing from one card to pay another; you feel relief on payday rather than possibility; you have no buffer, so a single surprise, a medical bill, a flight home, a car repair, goes straight onto credit.”
Don’t stop saving completely
While paying down debt is important, Jain said youth should also maintain some savings, even if the amount is small.
An emergency fund can help cover unexpected costs without forcing someone to rely on another credit card or loan, he said.
Antoinette also advised treating savings as a priority rather than whatever remains at the end of the month.
Another risk is increasing spending every time income rises, he said, as lifestyle inflation can leave people earning more but still struggling to make it to the end of the month.
Both experts also warned against using available credit to finance a lifestyle that is beyond a person’s means, particularly when it comes to expensive cars and other depreciating assets.
Jain said people should not mistake the amount of credit available to them for money they can afford to spend.
For those already in debt, the immediate priority is therefore not finding another source of credit, but understanding exactly what they owe, protecting essential expenses, tackling expensive debt and creating enough financial breathing room to avoid falling back into borrowing.


Azza Al Ali is a reporter from Ras Al Khaimah, dedicated to sharing stories that bring the community’s voices to life. She’s passionate about connecting with people and highlighting what truly matters to them.