 E-Paper
 Sign In


Can the Digital Dirham become more than just another way to pay?
The UAE is betting its central bank digital currency can reshape cross-border settlement, trade finance and digital finance, even as consumers already enjoy near-instant payments
- PUBLISHED: Thu 27 Aug 2026, 10:44 AM
- By:
- Suneeti Ahuja-Kohli


The UAE does not have a payments problem. Consumers can transfer money instantly, tap cards, use mobile wallets and increasingly pay through Aani, while banks and fintechs have spent years making digital transactions faster and more seamless.
That makes the central question surrounding the Digital Dirham less about what it can replace than what it can do that existing financial infrastructure cannot.
Recommended For You
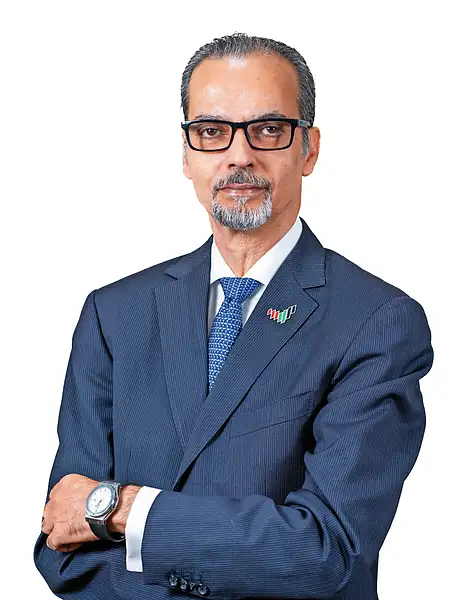
Jamal Saleh, Director-General of the UAE Banks Federation, sees it not as a replacement for cards, bank transfers or instant payments, but as a new layer of sovereign digital money.
“The UAE already has one of the world’s most advanced payment ecosystems,” says Saleh.
“The Digital Dirham complements the advanced payments ecosystem by providing a sovereign-backed digital currency that strengthens security, resilience and financial innovation.”
The ambition extends well beyond retail payments. The Central Bank of the UAE’s Financial Infrastructure Transformation programme has been developing wholesale and retail applications, including wallets, peer-to-peer and merchant payments and smart-contract services.
For businesses, particularly SMEs, the attraction could be more tangible. The Digital Dirham could enable instant settlement, lower transaction costs, improved liquidity management and programmable payments. Smart contracts could trigger payments automatically when agreed conditions are met, potentially streamlining trade finance, supply chains and other conditional transactions.
For banks, meanwhile, the technology could create new commercial opportunities rather than simply cannibalise existing payment revenues. Digital wallets, treasury and cash-management products, automated payroll, trade finance and supply-chain payments could become new services, while banks could participate in tokenised assets through custody, settlement and advisory services.
“As banks successfully transitioned to digital banking, they can build new business models around digital currencies, embedded finance and tokenised financial services,” notes Saleh.
The UAE’s two-tier model is central to that proposition. Commercial banks and licensed financial institutions will remain the customer-facing layer, providing onboarding, wallets, customer service, compliance and financial products. Saleh argues that their broader role in credit creation, financial intermediation and risk assessment cannot be replaced by a CBDC.
But retail adoption may prove harder.
“International experiences demonstrate that introducing a CBDC does not automatically change consumer behaviour,” Saleh says.
“People adopt new payment methods when they are more convenient, rewarding, or provide value not offered by existing options.”
In a market where existing payments are already fast and convenient, another way to pay may not be compelling enough. The Digital Dirham will therefore have to demonstrate value beyond speed.
The bigger opportunity may lie across borders.
For the UAE, a global trading and financial hub, faster and cheaper settlement could reduce some of the friction associated with correspondent banking and international transactions. Project mBridge has already tested multi-CBDC cross-border payments, while the UAE sees potential for stronger digital-payment and local-currency links with the GCC, India, China and other trading partners.
“The Digital Dirham can become an important settlement instrument with UAE trade partners with strong economic integration, regulatory alignment and a shared commitment to digital financial infrastructure,” Saleh says.
The Digital Dirham will also have to coexist with private digital money. Saleh sees sovereign digital currency and regulated dirham-backed stablecoins as complementary: the former providing a trusted settlement foundation, the latter enabling private-sector innovation in digital commerce, tokenised assets and decentralised finance.
Trust will be equally important. Saleh says privacy protections are built into the system, with commercial banks and licensed payment providers managing customer relationships and transaction processing, while access to transaction data remains governed by legal and regulatory requirements.
The transition is expected to be gradual, with wholesale banking applications and pilots preceding broader retail adoption, potentially towards the end of the decade.
“The determining factor is not technology or regulation,” says Saleh. “The UAE has one of the world’s most advanced digital payment ecosystems.”
That leaves the Digital Dirham with an unusual challenge. It must compete not with a broken payments system, but with one that already works very well.
Its ultimate success may therefore have little to do with whether consumers abandon their cards or banking apps. The bigger test is whether the Digital Dirham quietly becomes the infrastructure underneath a new generation of programmable, cross-border and tokenised finance.