 E-Paper
 Sign In


Banks will shape the next phase of digital money
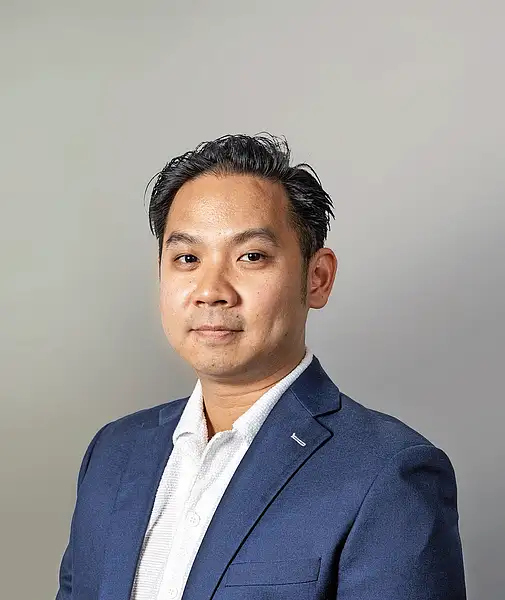
As the UAE races to build a regulated digital asset ecosystem, Zand says that the future lies in the tokenisation of trade, where stablecoins, tokenised assets and blockchain infrastructure are reshaping the way value moves through the economy
- PUBLISHED: Thu 27 Aug 2026, 10:50 AM
- By:
- Suneeti Ahuja-Kohli


The digital asset industry is entering a new phase, and it may be banks that emerge as the key drivers for the next stage of growth.
Mark Ng, who leads digital assets at Zand, an AI and blockchain-powered digital bank in the UAE, argues that the next stage of blockchain adoption will no longer be driven by speculative trading but by regulated financial institutions embedding stablecoins into everyday commerce.
Recommended For You
“The tokenisation of individual assets is only one part of the equation,” says Ng, adding, “Stablecoins serve as a trusted settlement layer, while tokenised real-world assets (RWAs) enable assets to be traded seamlessly on blockchain networks. Together with secure and compliant digital infrastructure, they form the foundation for the tokenisation of trade.”
Globally, governments and financial institutions are accelerating efforts to build regulated digital payment infrastructure. The UAE has positioned itself among the world’s most active jurisdictions for digital assets, with regulators including the Central Bank of the UAE and Dubai’s Virtual Assets Regulatory Authority (VARA) creating dedicated licensing regimes.
In the UAE, Zand’s UAE dirham-backed stablecoin, AEDZ, has reached hundreds of millions in circulation within months of its launch, according to the bank.
Rather than viewing blockchain as a parallel financial system, Ng argues that banks and treasuries increasingly see it as a more efficient payment rail.
Banking meets crypto
The past year has marked an important shift, says Ng, as mainstream finance and crypto-native firms increasingly converge.
Banks are launching stablecoins and tokenised deposits, while digital asset companies are expanding beyond cryptocurrencies into tokenised stocks, commodities and other traditional financial products.
“The line between finance and digital assets is beginning to blur,” notes Ng.
“Crypto super-apps which used to offer spot and derivative trading of cryptocurrencies are now starting to offer stocks and traditional financial products. At the same time, banks and conventional brokers are moving into virtual assets.”
The convergence reflects broader industry trends. Stablecoins, which are known to be digital tokens whose value is pegged to fiat currencies, have grown into one of crypto’s largest sectors, with global circulation now exceeding $300 billion according to the data from the World Economic Forum. The transaction volume exceeded $34 trillion in 2025, as per Visa.
Cross-border payments remain the prize
Although stablecoins are increasingly being discussed for domestic payments, Ng believes their strongest commercial case remains international transactions.
Traditional cross-border liquidity models require financial institutions to pre-fund accounts across multiple jurisdictions, tying up capital that could be deployed more efficiently through blockchain-based settlements.
Much of AEDZ’s current activity comes from users moving funds between banking and blockchain ecosystems, although the bank expects broader business-to-business payment applications to emerge.
Stablecoins will complement money, not replace it
Despite rapid growth, Ng dismisses suggestions that stablecoins could eventually displace sovereign currencies. Instead, he compares different forms of money to different modes of transport.
“Cars, trains and airplanes all move people, but they serve different purposes based on factors such as distance and number of passengers,” he says, adding, “It’s similar with cash, central bank digital currencies and stablecoins. They are all money, but each are suited for different use cases.”
Ng expects central bank digital currencies (CBDCs) to remain largely focused on domestic payments where national policy objectives can be programmed into token, while privately issued, regulated stablecoins are likely to be the preferred instrument for cross-border settlements.
The next measure of success
Three years ago, success for digital assets meant obtaining regulatory clarity.
Today, that milestone is increasingly being achieved especially in the UAE. The next test for the industry, Ng argues, will be whether more banks or financial institutions adopt Zand’s vision to offer both conventional banking and blockchain-based financial services.
“One measure of the industry’s success is how many banks adopt a model similar to Zand’s,” he said.
“It won’t be an overnight switch. Banking and financial services are usually deeply entrenched due to the company’s policies and infrastructure as they are designed to be robust and highly regulated.”
He also expects investors and policymakers to pay increasing attention to a new category of neobanks operating entirely on blockchain and stablecoin infrastructure. Representing a fundamentally different model from traditional banking, their long-term success will depend on how they fit into regulatory frameworks.
Stablecoins will be the future of money, and the journey is only just beginning.