 E-Paper
 Sign In


From 3 days to 3 seconds: How UAE’s remittances industry has evolved
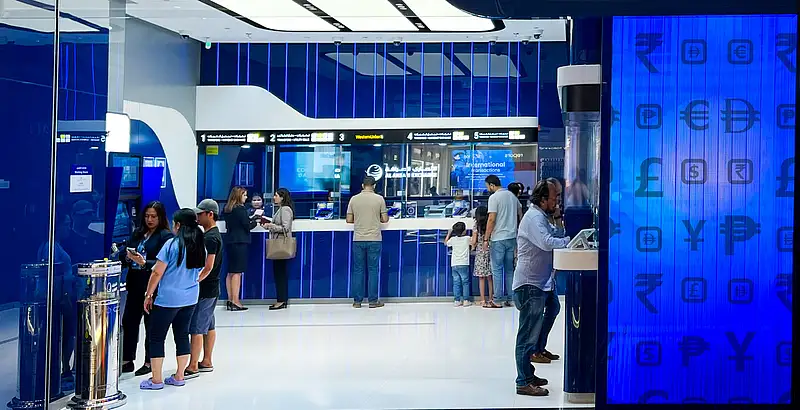
From paper ledgers and three-day transfers to instant remittances, Rashed A. Al Ansari, Group CEO of Al Ansari Financial Services, narrates the story of how the sector has evolved
- PUBLISHED: Tue 18 Aug 2026, 5:59 AM UPDATED: Tue 18 Aug 2026, 5:01 PM


Imagine needing cash urgently to send home to a sick family member – and having to wait three days for it to arrive. That was the reality for expatriates in the UAE back in the 1960s, when Al Ansari Exchange first opened its doors. Today, the same transfer can land in three seconds.
“I remember it used to take a very long time. It was three days,” recalls Rashed A. Al Ansari, Group CEO of Al Ansari Financial Services, describing the early days of paper ledgers, carbon copies and traveller’s cheques. “Now it’s instant. By the time you touch the door handle of the branch to go out, it’s already credited to the beneficiary's account.”
Recommended For You
The UAE’s remittances industry has evolved substantially over the past five decades, driven by technological advancements that have made transfers from the UAE to many recipient countries virtually instant.

The UAE is one of the world’s largest markets for remittance outflows, with billions of dollars sent abroad annually, as most expats – who account for around 85 per cent of the country’s population – remit money to support their families in their home countries.
Importantly, the financial services industry has evolved in multiple directions. When families travelled to any other country, they used to carry a huge stack of cash to hotels and while moving around the country.
With the introduction of travel cards, individuals and families can load thousands of dirhams and go around their shopping and enjoy the travel and tourism. They can also withdraw cash from ATMs, as and when required.
“Travel should be about enjoying the journey, not worrying about how to access or carry foreign currency. We are proud to make that experience simpler, safer and more convenient for our customers,” Rashed added.
With technological advancements comes stricter compliance.
“The biggest challenge to speed today isn’t technology but compliance, says Rashed.
Real-time checks on senders and receivers, required to detect suspicious names or accounts, sometimes require a manual review when there is a partial match. To address this, the company is now turning to AI, which can compare details such as dates of birth in a split second to clear false alarms that would otherwise require a human to review.
Crossing 300 branches
The Al Ansari story goes back to 1966. The founder was originally in the food trading business, bringing supplies into the region. But as the UAE’s oil boom drew waves of expatriate workers eager to send money home, Al Ansari saw an opportunity – and used his existing trade networks to start moving money instead. He obtained his licence from the Emirate of Abu Dhabi five years before the UAE was even formed and opened the first branch in Abu Dhabi’s Central Market.
Narrating his school-day experiences, Rashed said he grew up around the business quite literally.
“I attended Al Ahmadiyah School, close to my father’s office. After school, I would often join him there before we headed home together, an experience that gave me an early and lasting connection to the family business.”
Those afternoons in the branch, watching his father deal with customers and even answering phone calls himself, planted the values that still guide the company: trust, reputation and delivering on a promise.
Six decades on, that small branch has grown into the UAE’s largest exchange and remittance company, with more than 280 branches and counting – and it is soon expected to cross 300.
“We’re not chasing a number. Our branch network continues to grow organically, guided by customer demand, while serving our customers and enhancing their experience remain at the forefront of our priorities.”
The group has also expanded into Bahrain, where it is now the largest player, as well as Kuwait and India. It recently acquired Bahrain’s BFC Group for $200 million and is awaiting regulatory approval to enter Oman.
Digital growth – 1% to 30%
When Al Ansari Exchange launched its app in 2018, barely 1 per cent of its remittances happened online. Then Covid-19 hit, and everything changed.
“Reaching even 1 per cent of our transactions through digital channels was once an important ambition for us,” Al Ansari says.
“Today, digital transactions account for around 30 per cent, and we expect this to reach 60 per cent over the next five years. In most months, our app alone processes more than 600,000 transactions, reflecting the rapid shift in customer preferences.”
Even so, plenty of customers – especially domestic workers and labourers – still prefer walking into a branch, whether due to habit, language barriers or simply not owning a smartphone.
Six decades, not a single fine
As the company marks its 60th anniversary this year, Al Ansari is especially proud that it has never been fined by the UAE Central Bank in 60 years of operation.
“We want to be a benchmark for others when it comes to compliance,” he says, adding that the company works closely with regulators to ensure new rules do not overburden ordinary customers.
