 E-Paper
 Sign In


Dubai hotel occupancy to recover in H2 2026 after sharp first-half decline
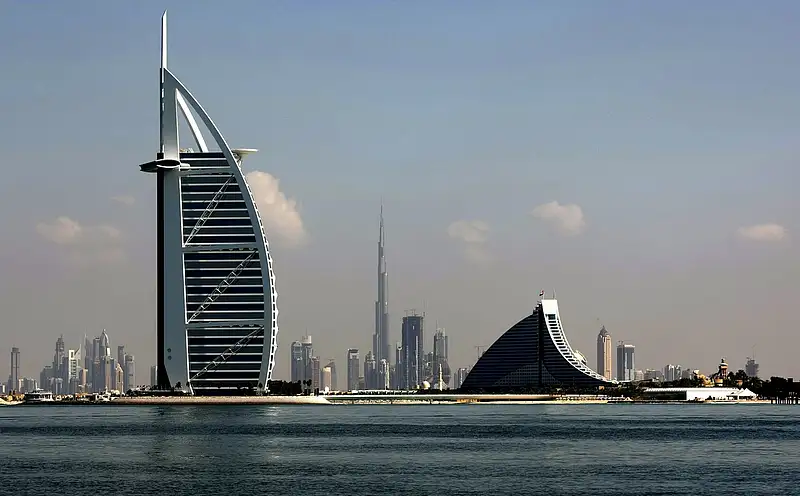
Early signs already point to a rebound in Gulf tourism, especially as aviation data is quickly recovering to pre-war levels, according to Capital Economics.
- PUBLISHED: Tue 18 Aug 2026, 2:48 PM


Dubai’s hospitality market is expected to gradually recover in the second half of this year, with full-year occupancy forecast within a range of 60.4 per cent–66.2 per cent, according to property consultant Cavendish Maxwell.
Average daily rates (ADR) are expected at Dh600–675, while annual passenger traffic is forecast at 67.6–79.3 million, remaining below the record levels achieved in 2025.
Recommended For You
The property consultant added that momentum is expected to pick up from Q4 as international air connectivity improves and the winter tourism season supports visitor demand.
Early signs already point to a rebound in Gulf tourism, especially as aviation data is quickly recovering to pre-war levels, according to Capital Economics.
Stay up to date with the latest news. Follow KT on WhatsApp Channels.
Steep decline in occupancy rates
Dubai’s hotel occupancy saw a 30.3 per cent in the first half of 2026 as the regional war and subsequent travel disruptions affected international travel demand, according to the consultant.
At the same time, passenger traffic at Dubai International Airport (DXB) declined by 31.7 per cent year-on-year during the first five months of the year to approximately 26.6 million as several international carriers paused operations amid regional instability.
Luxury and Upper Upscale hotels recorded the largest decreases, with occupancy averaging 51.2 per cent and 51.8 per cent, respectively, while the Upper Midscale segment remained the strongest performer at 65.7 per cent. Upscale and Midscale hotels recorded occupancy levels of 58.7 per cent and 63.7 per cent, respectively.
Average daily rates relatively contained
While occupancy rates saw a steep decline, citywide ADR fell 7 per cent year-on-year to Dh701, remaining comparatively contained.
This number suggests that hotel operators across segments prioritised rate preservation over volume and broadly avoided aggressive discounting to stimulate demand, Cavendish Maxwell noted in its report.
By segment, Luxury hotels continued to command the highest room rates despite a 6.2 per cent decline, while the Upper Upscale segment proved the most resilient, with ADR easing by just 2 per cent. The Upscale, Midscale and Upper Midscale segments also recorded moderate declines of 3.1 per cent, 2.4 per cent and 4.4 per cent, respectively.
This pricing discipline has helped protect the overall rate base and could support a more meaningful recovery in revenue performance once occupancy levels normalise.
Hotel supply remains stable
As per Cavendish Maxwell’s data, hotel establishments only saw a 1 per cent decline and a marginal 0.3 per cent reduction in room inventory compared with year-end 2025. This was mainly due to several hotel closures which offset new openings. In the first half, Dubai’s hospitality market comprised 727 hotels and approximately 152,139 rooms.
Government support also provided relief to the sector, with economic support packages totalling Dh2.5 billion combining fee relief for operators with targeted demand-stimulation measures.

Hind Aldah is a business reporter based in Sharjah. In her spare time, you will find her playing classical guitar, painting amateur oil paintings, or crocheting the same old scarf that leads nowhere.