 E-Paper
 Sign In




The e-invoicing countdown begins as October 30 is approaching
With the October deadline drawing closer, the transition is moving from policy to practice, giving businesses an opportunity to modernise finance operations while preparing for a more connected digital economy
- PUBLISHED: Wed 23 Sept 2026, 8:00 AM


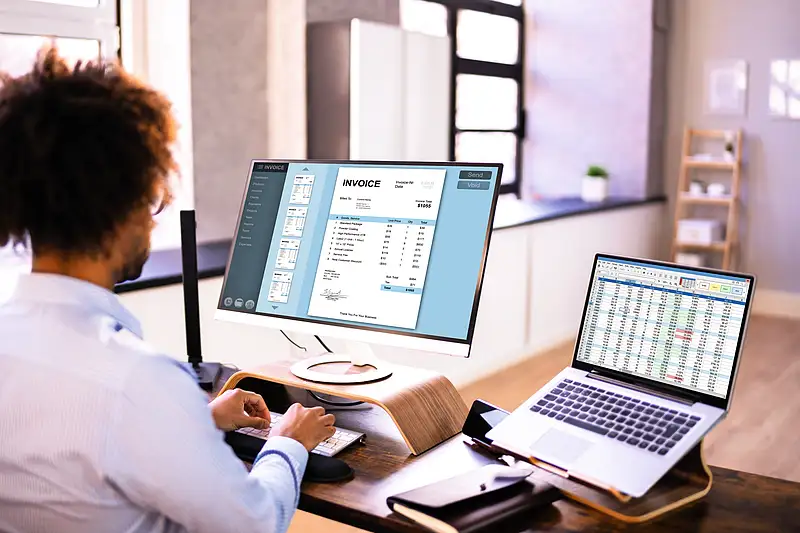
For years, companies have talked about digitising finance. Enterprise systems have moved to the cloud, payments have become faster and reporting has become increasingly automated, yet one of the most basic commercial documents — the invoice — often continues to move between businesses as a PDF attached to an email.
The UAE’s e-invoicing programme is about to change that.
Recommended For You
For businesses with annual revenue above Dh50 million, October 30, 2026 is the next important date. By then, they must appoint an Accredited Service Provider, or ASP, ahead of mandatory implementation from January 1, 2027. The Ministry of Finance extended the original July 31 appointment deadline after assessing market readiness and considering feedback from businesses seeking a wider range of technical solutions and more competitive pricing. The January implementation date, however, remains unchanged.
The extension comes as the market around e-invoicing is expanding quickly. When the change was announced in May, 32 service providers had already been approved and a significant number of others were in the final stages of accreditation. That gives companies more choice, but also makes the next few weeks important for deciding which provider best fits their existing finance and technology environment.
What makes the transition significant is that this is not simply a switch from paper to digital invoices. A PDF sent by email may be digital in everyday language, but it is not an eInvoice under the new framework. The new system is built around structured data that can move electronically from one business system to another, reducing the need for people to re-enter information, reconcile different formats or repeatedly check the same transaction. In that sense, the invoice is becoming part of the UAE’s wider digital infrastructure.

From document to data
The system uses a Peppol-enabled model in which suppliers and buyers exchange structured invoices through accredited service providers. The four-corner exchange connects the supplier, the supplier’s ASP, the buyer’s ASP and the buyer, while an additional tax-reporting capability enables the required information to reach the Federal Tax Authority. The Ministry of Finance has positioned the architecture around interoperability, security and the ability to scale as adoption increases.
For companies, that changes invoicing from a document-handling exercise into a data process. The difference may appear technical, but it has practical consequences. When invoice information follows a standard structure, it can move more easily between accounting systems, be validated earlier and reach the next stage of the payment cycle without somebody copying information from one screen to another.
Younis Haji AlKhoori, Undersecretary of the Ministry of Finance, said: “This milestone reflects the UAE’s continued commitment to advancing its digital financial ecosystem in line with global best practice. The introduction of the e-invoicing 4-Corner model enhances the efficiency and transparency of business transactions, while strengthening compliance and enabling seamless integration across the tax ecosystem. We encourage businesses to proactively adopt this system and benefit from its capabilities as part of the UAE’s broader vision to enhance its competitive, future-ready economy.”
Businesses are already beginning to look at the reform in those broader terms. At the UAE E-Invoicing Boot Camp 2026 in Abu Dhabi in August, regulators, tax specialists, finance executives and technology providers focused heavily on system readiness, governance and the operational changes required before implementation. The discussion reflected a noticeable shift in the market: companies are moving beyond asking what e-invoicing is and are increasingly examining how it will work inside their organisations.
“The key consideration for businesses is preparing their systems and processes for implementation,” said Muhammad Aaliyan Ibrahim, Managing Partner at ADEPTS Chartered Accountants. That preparation reaches much further than the finance department.
Customer and supplier master data needs to be accurate. Tax identifiers and mandatory invoice fields need to be available in the right places. ERP and accounting systems must be able to create structured invoices consistently, while companies also need processes for credit notes, rejected invoices, adjustments and other exceptions.
Older systems may require more work. Large groups may also discover that subsidiaries have developed different billing practices over the years, or that customer information is recorded differently across business units. E-invoicing creates a reason to address those inconsistencies because automated exchange depends on reliable data.
This is one reason the transition increasingly resembles a finance-transformation project rather than a narrow tax exercise.
Choosing the right ASP
The Accredited Service Provider sits at the heart of the new model and will become an important technology partner for businesses entering the system.
The Ministry of Finance requires providers to satisfy accreditation criteria covering technical capability, security and conformance with the e-invoicing framework. For companies selecting one, however, accreditation is only the starting point. The more practical questions concern fit.
A business needs to understand how easily a provider can integrate with its existing ERP or accounting software, how much implementation work will be required, whether it can handle expected transaction volumes and what happens when an invoice fails validation. Technical support, security, scalability and experience with complex business structures may prove just as important as price.
For a smaller company using a modern cloud accounting platform, onboarding may be relatively straightforward. A large multinational operating several entities and multiple ERP environments is dealing with a very different project.
The growing ASP market should work in businesses’ favour. More accredited providers mean greater choice around integration approaches, commercial models and specialist expertise. The deadline extension was partly intended to allow that market to develop and give businesses better options.
It is still worth starting early. Appointing an ASP by October 30 does not complete the transition. Contracts have to be finalised, connections built, data tested and users prepared before January 1.
The voluntary pilot, which began on July 1, is already giving participating businesses an opportunity to test those processes before the first mandatory phase. Early experience is also helping companies understand where the real work lies: not simply in transmitting an invoice, but in making sure the data and workflows behind it are ready.
Industry discussions this year have placed particular emphasis on governance.
Muhammad Rizwan Khan, Senior Partner and Global Compliance Head at AJMS Global, told the Abu Dhabi boot camp that regulatory requirements should be built into governance structures, internal controls and normal business processes rather than treated as a separate compliance activity. That approach could prove valuable well beyond the January deadline.
The regulatory timetable naturally gives the transition urgency. Businesses above the Dh50 million revenue threshold need to appoint their ASP by October 30 and begin mandatory e-invoicing on January 1, 2027. Businesses below the threshold have until March 31, 2027 to appoint a provider, with mandatory implementation starting on July 1. Government entities within scope also have a March 31 appointment deadline, with implementation from October 1, 2027.
There are also defined consequences for missing the requirements. Failure to implement the system, including failure to appoint an ASP within the prescribed period, can result in a penalty of Dh5,000 for each month or part of a month of delay. Once a business is required to issue electronic invoices, failure to issue and transmit one within the required timeframe can attract a Dh100 penalty per invoice, capped at Dh5,000 in a calendar month.
For most companies, however, the stronger reason to prepare early may be operational rather than punitive. A poorly tested connection can lead to rejected invoices, manual corrections and delays in processing. If invoices are held up, payments can follow. For organisations handling thousands of transactions, small problems repeated at scale can create unnecessary pressure on accounts receivable, accounts payable and working capital.
The positive side of the same equation is considerable. A well-designed implementation can remove manual steps that businesses have lived with for years. Finance teams routinely spend time keying invoice data, checking tax details, matching documents and resolving discrepancies. Structured exchange offers an opportunity to automate more of that work and identify errors earlier in the cycle.
The benefits extend into cash-flow management. Cleaner and faster invoice processing can shorten the distance between raising an invoice and receiving payment, while more consistent data can improve visibility over receivables and payables. Stronger audit trails can also make reconciliation and reporting easier.
The wider industry discussion is increasingly reflecting this opportunity. The Abu Dhabi boot camp highlighted growing investment in tax technology, digital governance and compliance systems, while speakers argued that finance professionals will need stronger digital capabilities alongside traditional accounting expertise.
The voluntary pilot has reinforced the same message. Businesses participating ahead of the mandate are using the period to examine their systems, clean data and test relationships with service providers, turning regulatory preparation into an opportunity to improve processes before implementation becomes compulsory.
Part of a bigger digital shift
E-invoicing also fits naturally into the UAE’s wider economic direction. Over the past several years, the country has moved rapidly in digital payments, electronic government services, tax administration and technology-enabled business processes. E-invoicing connects another piece of that infrastructure by creating a common language for invoice data.
Once transactions are structured consistently, the potential goes beyond invoicing itself. Procurement, payments, accounting, tax reporting and analytics can all work more effectively when the underlying data is clean and machine-readable.
This is particularly relevant for an economy built around international trade. The use of Peppol standards gives the UAE framework an interoperability dimension that can support increasingly digital commercial relationships across borders.
A recent assessment of the pilot by Hanadi Khalife, Regional Director of MEASA at ICAEW, placed e-invoicing within the same broader trajectory as the UAE’s investment in ports, airports, free zones and modern tax administration. The underlying point is that the infrastructure for doing business has to evolve alongside the economy it serves.
The transformation should also change the role of the finance function. When fewer hours are spent moving information manually between systems, finance professionals can devote more attention to analysis, forecasting, working capital and business decisions.
For SMEs joining in the later phase, the adjustment may be different in scale but not necessarily in direction. Cloud-based accounting platforms and an expanding ASP market could make adoption more accessible, while greater automation can be particularly valuable to smaller businesses that do not have large finance teams.
The UAE has deliberately phased the rollout rather than moving the entire market at once. Large organisations go first, smaller businesses follow, and the provider ecosystem has time to develop alongside them. That measured approach gives companies the opportunity to learn from early adopters while giving technology providers time to refine their offerings. For businesses in the first wave, however, the planning horizon is now much shorter.
October 30 is approaching, and the more important January 1 go-live date sits close behind it. Companies that are already choosing providers, cleaning data and testing systems will enter that transition differently from those that treat the ASP appointment as the end of the exercise.
The larger opportunity is to use the mandate to fix processes that were ready for improvement anyway. E-invoicing may begin as a regulatory requirement, but its legacy could be a finance environment that is faster, more automated and easier to analyse. The UAE is effectively turning one of the oldest commercial processes into another piece of its digital economy.
AlKhoori has encouraged companies to approach the change in precisely that spirit, urging businesses to “proactively adopt this system and benefit from its capabilities” as the country builds a more competitive and future-ready economy.
For companies preparing for the first deadline, that may be the most useful way to view the countdown. January 1 is not simply the day a new invoicing rule takes effect. It is the beginning of a different way of moving financial data through business.

Sana Eqbal is a journalist and media strategist with over a decade of experience at the intersection of media, business and emerging technologies. She specialises in corporate communications, digital storytelling, public relations and AI-powered content strategy.